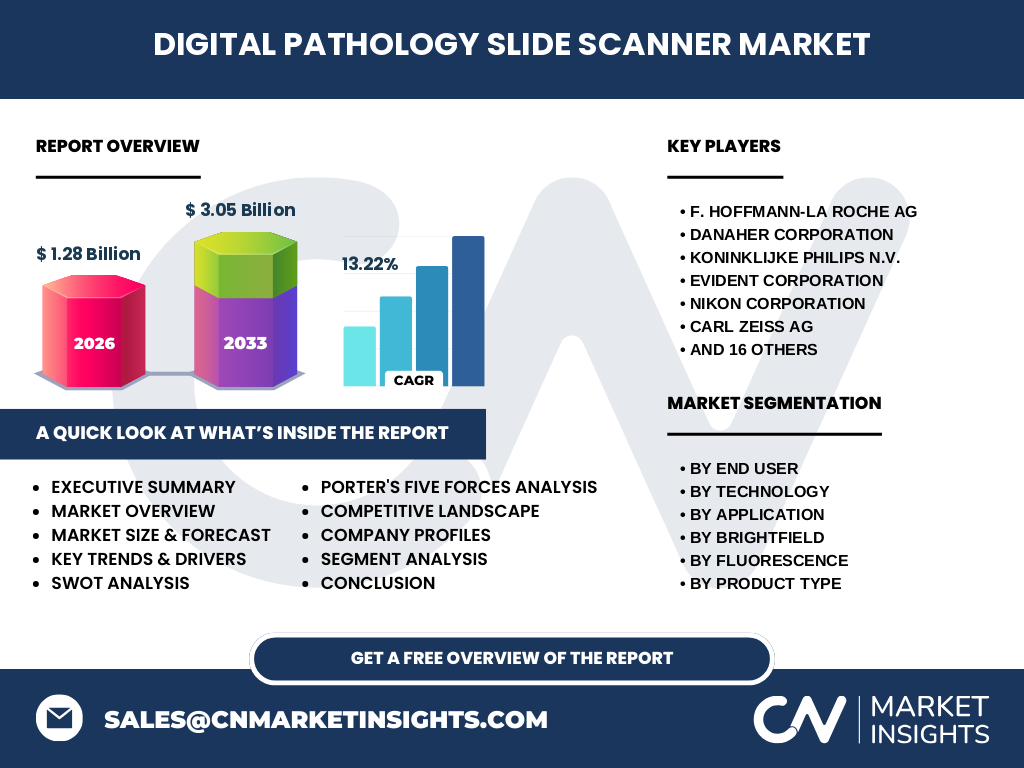
Market Overview of the Digital Pathology Slide Scanner Market
Our analysis indicates that the Digital Pathology Slide Scanner Market represents a transformative paradigm in diagnostic medicine, converting glass slides into high-resolution diagnostic images. Valued at 1.28 Billion in 2026, the industry is underpinned by stringent regulatory bodies like the FDA and EMA. This ecosystem facilitates telepathology, primary diagnosis, and advanced computational staining, revolutionizing traditional workflows across global healthcare infrastructures.
Structural Growth Drivers and Market Restraints
The market is propelled by a rising global cancer burden and a severe shortage of specialized pathologists. Key growth drivers include AI integration and remote diagnostics. Conversely, market restraints involve exorbitant initial capital outlays for high-capacity scanners and complex regulatory approval pathways for software-as-a-medical-device (SaMD) platforms, creating severe entry barriers for emerging hardware manufacturers.
Emerging Industry Trends in Digital Pathology Slide Scanner Market
The data suggests an accelerating shift toward cloud-based computational pathology and multi-modal imaging systems. Innovations combining brightfield and fluorescence capabilities are gaining rapid traction. Companies like Proscia Inc. and Paige.AI are pioneering AI workflows that streamline high-throughput slide imaging, drastically reducing diagnostic turnaround times in major clinical laboratories worldwide.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic acted as an unprecedented catalyst for the Digital Pathology Slide Scanner Market industry trends. Lockdowns and social distancing mandated remote working environments, forcing pathology departments to adopt digital workflows out of sheer necessity. Post-pandemic recovery has stabilized into robust long-term digital transformation budgets, permanently altering historical procurement cycles in hospital networks globally.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, dominated by established medtech giants and agile software innovators. Industry leaders such as F. Hoffmann-La Roche AG, Danaher Corporation, and Koninklijke Philips N.V. leverage extensive global distribution networks. Meanwhile, specialized challengers like Scopio Labs Ltd. and Morphle Labs Inc. compete aggressively through disruptive AI-powered optics and proprietary slide capacity architectures.
Executive Summary of the Digital Pathology Slide Scanner Market
Our comprehensive research underscores an explosive trajectory for the sector. Driven by surging clinical adoption and technological maturation, the market is poised to expand from 1.28 Billion in 2026 to 3.05 Billion by 2033, registering a remarkable CAGR of 13.22%. Strategic investments in AI and hyperspectral optics remain critical for capturing high-margin opportunities.
Long-Term Market Forecast from 2027 to 2033
Based on our research, the market will experience accelerated expansion over the forecast period. Scaling from 2027 through 2033, revenues are projected to surge toward the 3.05 Billion milestone at a stellar CAGR of 13.22%. This upward trajectory is fueled by widespread hospital digitization grants and expanding reimbursement frameworks for telepathology consultations across North America and Western Europe.
Comprehensive Segmentation Analysis
The market is meticulously segmented across multiple critical vectors. By End User: Hospitals, Diagnostic Laboratories, Academic And Research Institutes, Pharmaceutical And Biotechnology Companies, and Other End Users. By Technology: Whole Slide Imaging, Live View Scanning, Z Stack Scanning, Confocal Scanning, and Other Technologies. By Product Type: Brightfield, Fluorescence, and Other Product Types. By Slide Capacity: Low, Medium, and High Capacity Scanners.
Geographic Distribution and Regional Performance
Regional performance varies significantly based on healthcare infrastructure maturity and reimbursement policies. North America commands the largest revenue share due to early tech adoption and well-funded hospital networks. Meanwhile, Asia-Pacific represents the fastest-growing regional market, driven by massive healthcare investments in China and Japan, supported by domestic innovators like Hangzhou KFBIO Biotechnology Co. Ltd.
In-Depth Regional Review of Key Markets
North America leads through robust integration of digital scanners within oncology networks. Europe follows closely, anchored by stringent centralized procurement and collaborative EU health initiatives. The Asia-Pacific region demonstrates exceptional growth potential, spurred by urban expansion and rising diagnostic standards, though logistical hurdles regarding regional importation laws remain prevalent in emerging Southeast Asian markets.
Strategic Positioning of Leading Companies
Industry participants employ diverse strategies to secure market dominance. conglomerates like Danaher Corporation and Hamamatsu Photonics K.K. focus on high-throughput hardware reliability. Concurrently, specialized software and hardware providers like Indica Labs, Visiopharm, and Huron Digital Pathology Inc. concentrate on advanced algorithmic analysis and modular, scalable slide scanning architectures.
Porter's Five Forces Analysis of the Sector
Competitive rivalry is intense among entrenched hardware manufacturers. Supplier power remains moderate due to specialized optical components and precision sensors. Threat of substitution is low given the clinical validation requirements of regulatory bodies. Buyer power is counterbalanced by the high switching costs associated with proprietary enterprise software ecosystems and integrated PACS networks.
SWOT Analysis of the Industry
Strengths include high diagnostic accuracy and efficient remote collaboration. Weaknesses involve high capital expenditure and stringent compliance hurdles. Opportunities lie in emerging markets and AI diagnostic integration. Threats encompass cybersecurity vulnerabilities in cloud pathology repositories and potential delays in medical device regulatory clearances by international health agencies.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with high-grade optical glass, precision lasers, and semiconductor sensors. Midstream manufacturing involves complex assembly by innovators like Nikon Corporation and Carl Zeiss AG. Downstream distribution flows through specialized medical logistics directly to hospitals, clinical labs, and biopharma giants conducting complex drug discovery pipelines.
Strategic Investment Insights and High-Potential Areas
Our analysis indicates that investors should prioritize companies developing AI-enabled hybrid and multimodal imaging systems. High-capacity scanners tailored for centralized diagnostic laboratories offer superior long-term yield. Furthermore, software-centric firms specializing in seamless enterprise interoperability present exceptional acquisition targets for large-scale medtech consolidators.
Conclusion and Strategic Key Takeaways
The Digital Pathology Slide Scanner Market analysis confirms a thriving, high-growth sector set to reach 3.05 Billion by 2033. Stakeholders must embrace AI convergence and modular hardware scalability. Organizations failing to integrate cloud-ready, high-throughput imaging systems risk obsolescence in an increasingly digitalized clinical pathology landscape.
Robust Research Methodology
Our baseline estimates are rigorously triangulated using a multi-tiered approach. This combines primary stakeholder interviews with key opinion leaders, exhaustive trade registry data across major global ports, and secondary macroeconomic indicators. Financial modeling cross-references corporate earnings reports with verified healthcare expenditure databases to ensure absolute market accuracy.
Scope of the Report and Coverage Parameters
This report encompasses a global evaluation of the Digital Pathology Slide Scanner Market market size across specified technology, application, and regional classifications. While covering historical data from past years, forward projections span strictly from 2027 to 2033. Macroeconomic disruptions, localized currency fluctuations, and varying regional reimbursement updates are factored into our analytical models.
Recent Industry Developments, Partnerships, and Product Launches
Recent strategic moves highlight an intense race toward AI integration and hardware miniaturization. Notable partnerships between diagnostics giants and AI developers—such as collaborations involving Sectra AB and specialized image analytics firms—demonstrate a unified push toward comprehensive, end-to-end digital pathology workflows designed to streamline clinical trials and routine hospital operations.